Wisr AI Systems Inc. offers an early public-market entry into commercial AI cybersecurity. Its reference equity value is approximately C$1.77 million. Against that starting point, enterprise customer wins and expanding paid RiskAssure adoption could materially change the scale of the business.
The company has launched RiskAssure, added Merchant Growth distribution and introduced paid Active Testing. Enterprise partnerships and defence-sector business development extend the opportunity beyond individual small-business purchases. My bullish case centres on converting these routes into customer agreements, repeat spending and larger deployments.
- Early commercial entry point: Wisr’s approximately C$1.77 million reference equity value creates sensitivity to meaningful customer wins.
- Several routes to growth: Marketplace distribution, enterprise partnerships and paid testing broaden the opportunities to generate revenue.
- Contract scale could matter: Four hypothetical agreements generating C$250,000 annually each would produce C$1 million in annual revenue.
Why the Starting Valuation Matters
| Reference metric | Figure |
|---|---|
| Listing | Canadian Securities Exchange: WISR |
| Reference quotation | C$0.025; November 3, 2026; delayed |
| Basic shares | Approximately 70.92 million; October 28 MD&A |
| Calculated equity value | Approximately C$1.77 million |
A small equity base can make commercial progress particularly consequential. An agreement establishing material customer spending could give investors firmer numbers for assessing Wisr’s prospects. Additional deployments and renewals could then strengthen confidence in the durability of that revenue.
This is the attraction of entering during commercialisation. Investors can assess the opportunity before a substantial revenue base becomes established. The low valuation alone does not establish that the shares are undervalued.
RiskAssure Addresses a Measurable Business Need
RiskAssure targets a practical obstacle for companies selling to larger organisations: completing security reviews and demonstrating their controls. Wisr says its platform analyses approved evidence, generates source-cited questionnaire answers and routes exceptions for human review. Its free trust centre and unlimited questionnaires provide an accessible starting point for prospective customers.
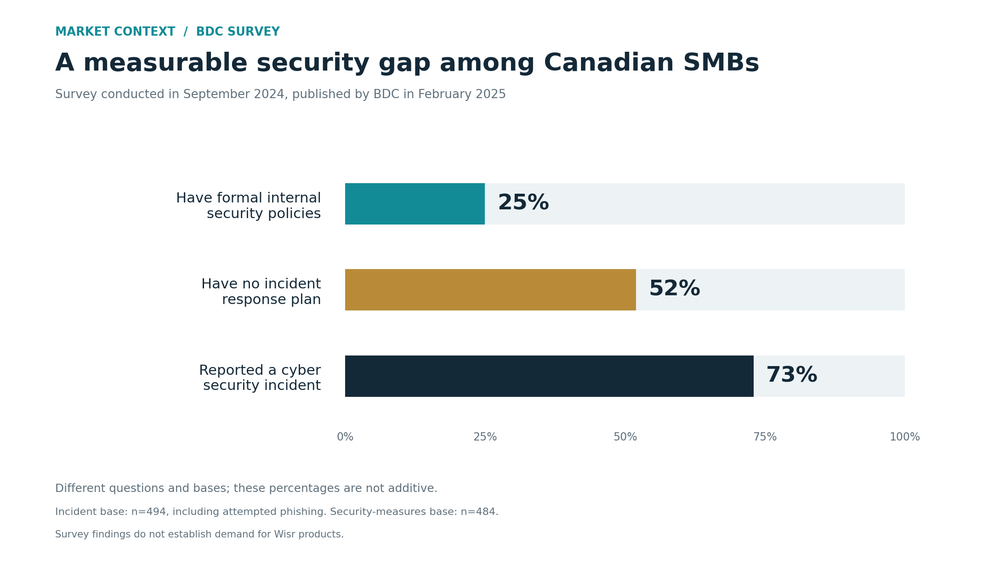
BDC’s September 2024 poll found that only 25% of respondents had formal internal security policies. 52% had no incident response plan. Separately, 73% reported a cybersecurity incident, including attempted phishing. These figures show room for stronger security preparation across Canadian small businesses.
Wisr’s opportunity is to connect that need with tools businesses can adopt and pay to expand. Active Testing adds a purchased service examining authorised public-facing applications and documenting vulnerabilities. It complements manual penetration testing and includes a retest of a remediated finding.
Two Distribution Channels Could Broaden Customer Acquisition
Merchant Growth has historically funded more than 15,000 Canadian small businesses. RiskAssure is available through its Merchants’ Market customer portal, which brings together more than 50 partners. That puts Wisr’s offering alongside services already used by its target audience. The historical reach belongs to Merchant Growth; it is not a Wisr customer count.
The enterprise opportunity gained another route when Wisr joined AI Partnerships Corp. in July. At announcement, its ecosystem included approximately 195 AI solution providers across 13 countries, serving more than 5,000 end users. Wisr identified referrals, co-selling and integration partnerships as potential commercial benefits. Those network figures describe AIP’s ecosystem.
| Commercial route | Potential growth contribution |
|---|---|
| Merchant Growth marketplace | Small-business adoption and purchases of paid services |
| AI Partnerships Corp. network | Enterprise introductions, reseller relationships and integrations |
| Direct RiskAssure sales | Customer relationships that can develop into repeat purchases or broader deployments |
My interpretation is that partner distribution could help Wisr reach customers more efficiently. Successful integrations could also introduce its technology into workflows already supported by other software providers.
Paid Adoption Could Build a Larger Revenue Base
The small-business opportunity can become meaningful without requiring a dominant market share. Assume C$1,000-C$2,000 in annual paid spending per organisation. These are illustrative inputs, rather than published prices or company guidance.
At 250 paying organisations, those assumptions produce C$250,000-C$500,000 in annual sales. At 500, they produce C$500,000-C$1 million. At 1,000, they produce C$1 million-C$2 million.
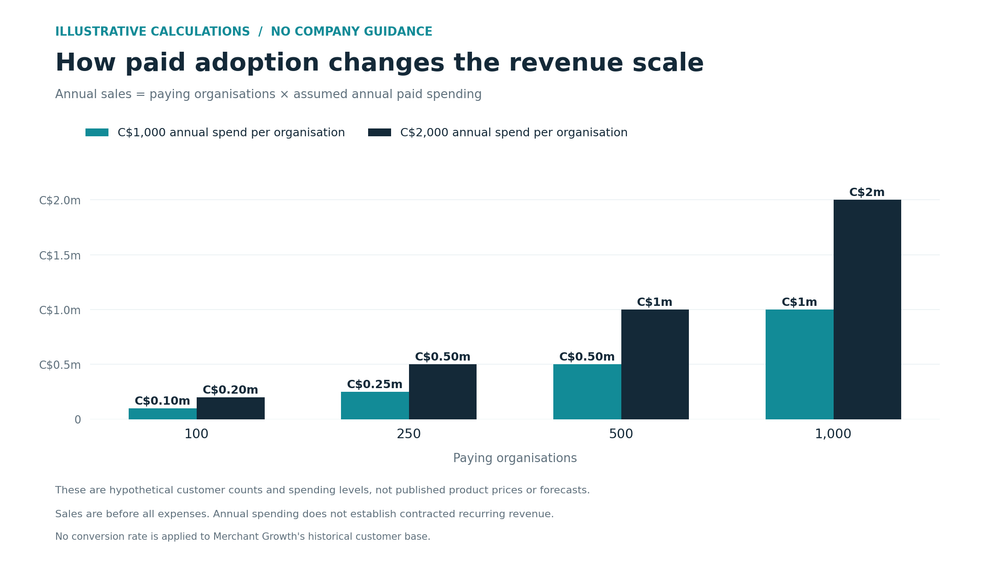
Repeat purchases could deepen the revenue opportunity after initial adoption. Contract terms and retention would determine how much spending becomes recurring revenue. These illustrations apply no conversion rate to either partner’s historical reach.
How New Contracts Could Change the Revenue Scale
Enterprise agreements offer another possible route to commercial scale. Wisr’s strategy includes enterprise customers, partner integrations and potential licensing opportunities. Its broader portfolio covers cyber-risk intelligence, security assurance and risk management.
To illustrate the sensitivity, assume an agreement generates C$250,000 in annual recognised revenue. One agreement would produce C$250,000 annually. Two would produce C$500,000. Four would produce C$1 million.
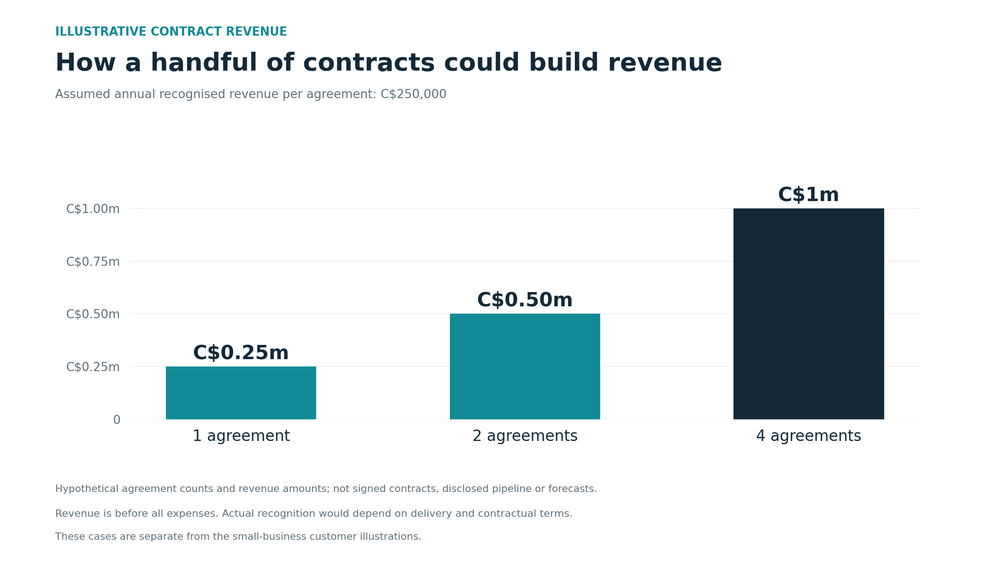
These are hypothetical agreements, not announced contracts or a disclosed sales pipeline. They illustrate how a handful of material wins could establish a substantially larger business. The contract cases are separate from the small-business illustrations above.
An agreement with minimum spending commitments could improve revenue visibility. Upfront customer payments could also help fund implementation. A successful deployment might support expansion across additional teams or vendor portfolios, depending on customer requirements.
That creates several potential catalysts within one relationship: an initial agreement, deployment, collected payments and subsequent expansion. Each could give investors more evidence for reassessing the business.
Defence Adds Another Commercial Opportunity
Wisr joined the Canadian Association of Defence and Security Industries in September. Management described opportunities to engage with government stakeholders, defence contractors and potential partners. It intends to pursue commercial pilots supporting cyber-threat and supply-chain risk applications.
The bullish interpretation is that this broadens the range of prospective customers beyond Wisr’s small-business offering. A pilot developing into a paid deployment could establish another source of demand. CADSI membership provides business-development access; its announcement does not establish a government contract award.
What Could Drive Shareholder Upside
My view is that meaningful contract wins could change how investors assess Wisr before full profitability arrives. A signed agreement would establish commercial terms. Deployment and cash collection would then help demonstrate the economics of delivery.
| Potential catalyst | Why it could support a higher valuation |
|---|---|
| A material enterprise agreement | Gives investors a defined customer commitment to assess |
| Partner-generated paid customers | Demonstrates that distribution can produce commercial results |
| Renewals or expanded deployments | Supports confidence in repeat demand and revenue durability |
| Revenue growth with proven margins | Creates a stronger basis for assessing future earnings |
If customer spending grows faster than delivery and acquisition costs, Wisr could develop a more scalable earnings profile. That is the financial outcome behind the bullish case. The size and timing of share-price upside would depend on agreements actually won, margins and future financing.
Capital for Commercialisation
July’s financing raised C$657,300, leaving C$627,600 after disclosed cash finder fees and before other costs. The raise supplied capital during the transition toward commercial sales. Customer receipts could become an additional funding source as deployments develop.
Wisr remains early-stage: its reported quarters through June recorded no revenue, and annual operating cash use was approximately C$970,000. Management expects additional financing during fiscal 2027, and the auditor identified material uncertainty related to going concern. Contract execution and financing terms therefore remain material to shareholder returns.
The Investment Case
Wisr offers exposure to commercial AI cybersecurity through a launched product and expanding sales channels. Meaningful contract wins could have an outsized impact from its roughly C$1.8 million reference equity base. For investors comfortable with early-stage risk, paid adoption and repeat deployments are the catalysts that could turn this opportunity into shareholder value.
Data Notes
Research checked November 4, 2026. Equity value uses a delayed November 3 C$0.025 quotation and 70,920,318 shares reported in the October 28 MD&A. It is not a live valuation or verified closing price. The exchange profile displays a different share count; subsequent issuance would change the calculation. Customer-spending and contract examples are hypothetical annual revenue before expenses, without assigned probabilities or price targets. They are separate illustrations, not an additive forecast. Product capabilities and network sizes are company-reported. Historical accounts do not establish current cash or runway.
Bullish investment commentary on a speculative microcap. Contract conversion, financing, dilution, liquidity and competition can materially affect returns. No price target or guaranteed outcome is assigned.
Marc has been involved in the Stock Market Media Industry for the last +5 years. After obtaining a college degree in engineering in France, he moved to Canada, where he created Money,eh?, a personal finance website.