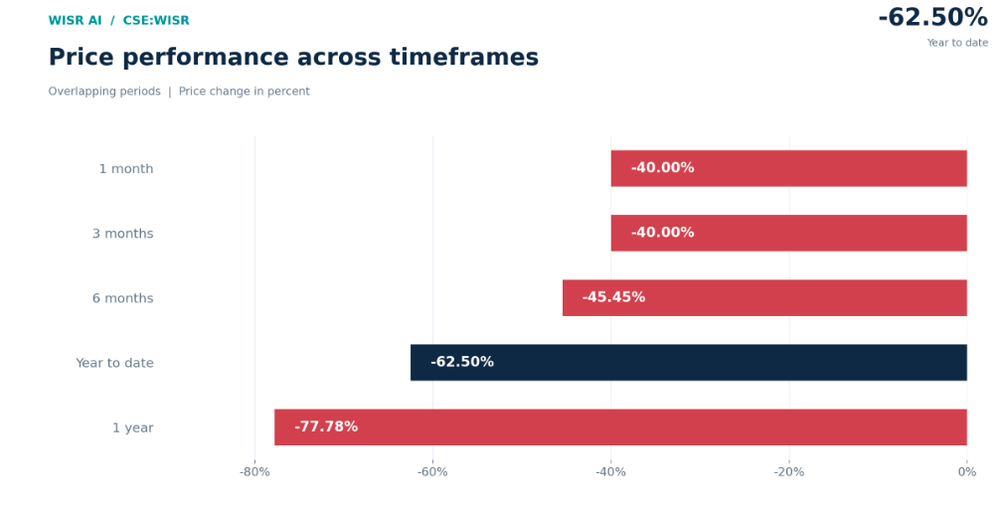
Wisr AI Systems trades at C$0.03, implying a market capitalisation of approximately C$2.11 million. Its shares have fallen 62.5% year to date, placing a small valuation against a business entering commercialisation.
RiskAssure launched in September. Distribution through Merchant Growth followed in October, alongside a separately purchased testing service. Investors now have concrete developments to assess against the company’s market value.
For investors comfortable with speculative technology companies, Wisr deserves attention as these commercial initiatives begin producing measurable results.
Three key takeaways
- C$2.11 million market cap: calculated using 70.43 million issued shares and the latest verified C$0.03 quote.
- A 62.5% YTD decline: recent commercial announcements have yet to reverse the broader share-price weakness.
- Three commercial milestones: a product launch, an additional distribution channel and paid testing provide clear developments to monitor.
The Stock-Market Snapshot
| Metric | Verified figure |
|---|---|
| Listing | CSE: WISR |
| Latest verified price | C$0.0300 |
| Calculated market capitalisation | C$2.113 million |
| Issued common shares | 70,432,818 |
| Shares reserved for issuance | 16,685,833 |
| Issued shares plus reserved shares | 87,118,651 |
| YTD performance | −62.50% |
| Reported 52-week range | C$0.025–C$0.180 |
The price and performance figures use the dated 21 October snapshot. Share counts come from the Canadian Securities Exchange.
The valuation calculation is straightforward:
C$0.03 × 70,432,818 shares = C$2,112,984.54.
Using the current share count matters. Some data providers still display approximately 57.59 million shares, producing a lower market-cap figure.
The issued-plus-reserved total provides additional dilution context. Actual future issuance depends on exercise terms, vesting and corporate actions.
What the Stock Chart Reveals
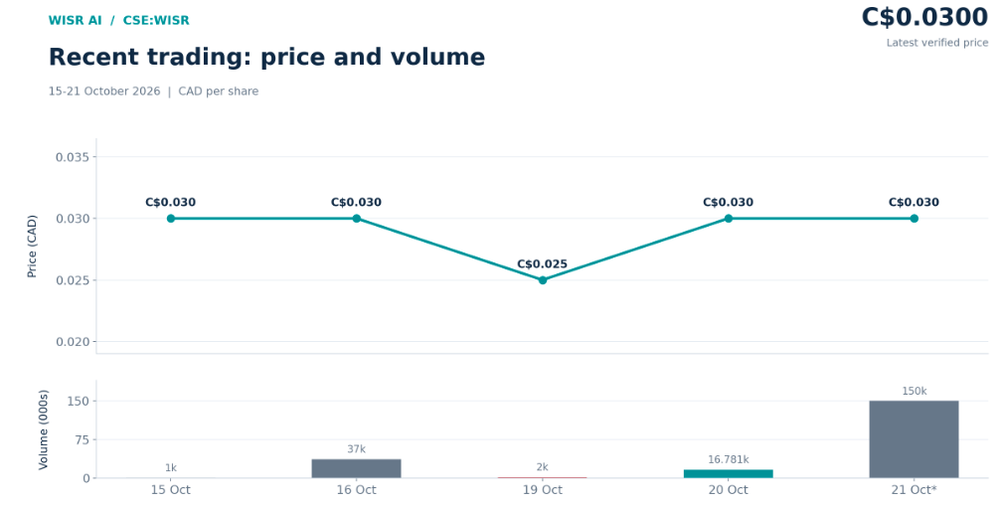
Wisr traded at C$0.025 on 19 October, before returning to C$0.03 on 20 October. That half-cent movement produced a 20% gain. At these prices, substantial percentage changes can result from small absolute moves.
Trading liquidity is equally relevant. Only 2,000 shares traded on 19 October. Using the reported 20-session average and C$0.03 reference price gives roughly C$2,928 in daily notional turnover. This is an approximation, rather than the sum of actual execution values.
For shareholders, this means order size and bid-ask spreads can materially influence execution.
The investment case therefore rests on improving commercial results. Wisr’s small valuation makes initial customer wins potentially significant, while financing and dilution will influence how that progress reaches shareholders.
A Commercial Product With a Route to Paid Services
RiskAssure offers a free trust centre and unlimited security questionnaires. Businesses can organise approved documents, control access to evidence and review AI-generated responses before sharing them. The platform flags answers requiring human attention.
This addresses a practical business problem. Suppliers seeking enterprise customers often need to demonstrate their security practices through questionnaires and supporting documentation.
On 15 October, Wisr added Active Testing as a separately purchased service. It tests authorised public-facing web applications, documents findings and connects the results with security-assurance workflows. Its scope complements manual penetration testing.
The potential commercial progression is clear: attract businesses through free tools, establish regular usage and sell additional services.
| Date | Confirmed development | Investment relevance |
|---|---|---|
| 10 September 2026 | RiskAssure commercial launch | Makes product adoption measurable |
| 8 October 2026 | Merchant Growth marketplace distribution | Adds a route to prospective users |
| 15 October 2026 | Paid Active Testing launch | Creates an additional monetisation opportunity |
These developments were announced in Wisr’s respective releases.
Distribution Could Become an Important Growth Driver
Merchant Growth has historically funded more than 15,000 Canadian small businesses. Its marketplace includes more than 50 partners, with services available through customers’ existing portals.
Those figures describe Merchant Growth’s reach. They do not represent Wisr customers or committed revenue.
My investment interpretation is that this channel could help Wisr reach relevant businesses more efficiently. The next evidence investors should seek is paid conversions, repeat purchases and revenue generated through the partnership.
For a company of Wisr’s size, establishing one productive distribution channel could meaningfully improve its commercial outlook.
Competitors Show the Market Opportunity
Vanta and UpGuard provide useful numerical context for the market Wisr is entering.
| Company | Disclosed financial or customer figures | Date and meaning |
|---|---|---|
| Wisr AI | C$2.11 million calculated market cap | Dated C$0.03 quote and current exchange share count |
| Vanta | US$4.15 billion financing valuation, US$150 million Series D and more than 12,000 customers reported | 23 July 2025 disclosure |
| UpGuard | $75 million Series C and more than 2,000 customers reported | 26 February 2026 disclosure |
Vanta’s figure is a historical private financing valuation. UpGuard’s figure measures capital raised; its cited release does not specify the currency. Neither figure represents a current quoted market capitalisation.
These figures demonstrate established commercial demand and well-funded competition. They cannot establish a valuation discount or price target for Wisr.
The product overlap is real. UpGuard offers vendor monitoring, questionnaire automation and trust-sharing tools. Vanta automates security reviews and compliance workflows. Bitsight and SecurityScorecard compete in cyber-risk intelligence, while Conveyor specialises in questionnaire automation and trust centres.
Wisr is the company to examine for exposure during this earlier commercial stage. Its appeal centres on the significance that initial paid adoption could have for a business valued near C$2.11 million.
The next competitive advantages must emerge through customer experience, distribution efficiency and retention.
The Financial Numbers Investors Must Follow
| Metric | Historical result |
|---|---|
| Reporting period | Nine months ended 31 March 2026 |
| Cash at period end | C$72,666 |
| Net loss | C$2,395,181 |
| Operating cash used | C$941,033 |
| Stock-based compensation | C$1,200,426 |
| Working-capital deficit | C$7,080 |
Operating cash use averaged approximately C$104,559 per month during that historical period. The net loss included substantial non-cash compensation and amortisation. The statements also disclosed material uncertainty about continuing as a going concern.
Wisr subsequently raised C$657,300 gross in July.
| July financing terms | Detail |
|---|---|
| Closing date | 21 July 2026 |
| Units issued | 13,146,000 |
| Price per unit | C$0.05 |
| Warrant component | Half a warrant per unit |
| Whole-warrant exercise price | C$0.075 |
| Warrant term | 18 months |
| Cash finder fees | C$29,700 |
The financing supplied additional capital for commercialisation and customer acquisition.
The C$0.03 share price is 40% below the financing’s headline unit price. Each unit also included half a warrant, so the packages are not equivalent.
The March financial figures predate July’s financing and September’s product launch. They cannot establish current cash runway or enterprise value. A verified current revenue run-rate was unavailable in the sources reviewed, limiting the usefulness of sales or earnings multiples.
Why Wisr Belongs on Investors’ Watchlists
Wisr now has a launched product, an additional distribution channel and a paid testing service. Those developments give investors concrete milestones to evaluate.
At approximately C$2.11 million, early commercial success could materially change the investment case. The next numbers that matter are paid customers, repeat spending, recognised revenue and updated cash resources.
That makes Wisr worth studying closely for investors seeking speculative exposure to cybersecurity commercialisation. Execution, financing terms and dilution will determine the strength of the opportunity.
For information only. Wisr is a speculative investment with substantial financing, liquidity, dilution and execution risks. Product capabilities and customer figures are company-reported. No price target or return forecast is assigned.
Marc has been involved in the Stock Market Media Industry for the last +5 years. After obtaining a college degree in engineering in France, he moved to Canada, where he created Money,eh?, a personal finance website.